Legacy
What Do You Really Want to Leave Behind?
When people talk about leaving a legacy, the conversation usually turns to money. How much will the children receive? How much will go to the grandchildren? Can taxes be reduced? Those are important questions. But I think there’s another one worth asking:What can you give them while you’re still here to enjoy it with them?
The Disney Story
Imagine a 65-year-old grandmother. She’s put aside $50,000 for her two grandchildren. She thinks of it as money for their future – perhaps college – and ultimately she wants them to have it. She doesn’t expect to spend the money herself. But she’s reluctant to simply give it away because life is unpredictable. She wants to maintain some protection if circumstances change. So we start asking questions. Is there another way to provide money for those grandchildren? Could insurance potentially increase the amount ultimately available to them? Could the strategy also provide certain living benefits if Grandma experienced a qualifying serious illness?
Does all $50,000 need to wait until Grandma dies?
Perhaps it doesn’t. Suppose an appropriate insurance strategy allowed her to accomplish her legacy objective using less than the entire $50,000. What could she do with some of the money that remains?
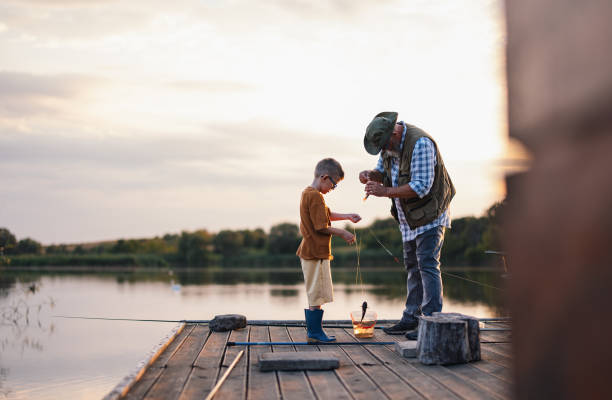
Take the grandchildren to Disney World.
Stay somewhere wonderful. Take the cruise. Buy the ridiculous souvenirs. Take too many photographs. Eat the overpriced ice cream. And create a memory those children may still be talking about decades later.
Someday they may inherit Grandma’s money. But they’ll never again have the opportunity to take that trip with Grandma.
Sometimes Money Is Supposed to Be Lived
Financial planning can become very mathematical: rates of return, tax consequences, death benefits and income. All of those things matter. But money is ultimately supposed to accomplish something. Sometimes that means providing financial security after we’re gone. Sometimes it means protecting ourselves while we’re alive. And sometimes it means going to Disney.
Leave something meaningful. Live something meaningful.
Can Life Insurance Increase a Legacy?
For the right person, properly designed life insurance can potentially turn an existing asset into a larger income-tax-free death benefit for beneficiaries under current federal tax rules. Certain policies may also provide access to benefits during life following qualifying events, depending upon the contract. But the example isn’t the recommendation. Age matters. Health matters. Liquidity matters. Taxes matter. Family circumstances matter. And the amount of money someone should keep readily available matters enormously. First we determine what that money needs to accomplish. Then we determine whether insurance improves the outcome.
Legacy doesn't have to mean children or grandchildren. For some people, it's a church, a university, an animal rescue, a medical organization, a community organization, or another cause that mattered throughout their life. There may be strategies that allow someone to provide more to an organization they care about than simply leaving the same amount of cash. What do you want your money to accomplish?
Tell me who matters to you. Tell me what you'd like to leave them. Tell me what you need to keep available for yourself. And tell me what you'd still like to experience while you're here. Then we'll look at the numbers. And only after that will we look at products.