Legacy
What Do You Really Want to Leave Behind?
When people talk about leaving a legacy, the conversation usually turns to money. How much will the children receive? How much will go to the grandchildren? Can taxes be reduced? Those are important questions. But I think there’s another one worth asking:What can you give them while you’re still here to enjoy it with them?
The Disney Story
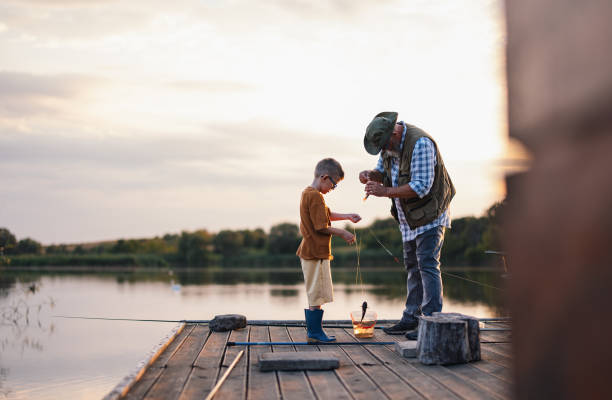
Imagine a healthy 65-year-old grandmother who has saved $50,000 for her grandchildren. She wants to leave them something meaningful, but she’d also love to take them on a wonderful family vacation while she’s here to enjoy it. What if she could do both? Suppose she qualifies for a single-premium life insurance policy costing approximately $35,000 that provides a $60,000 death benefit for her grandchildren. That leaves approximately $15,000 to enjoy today—perhaps taking the entire family to Disney and creating memories they’ll treasure for years. And when Grandma passes away, her grandchildren could still receive $60,000, more than the original amount she intended to leave them. Sometimes good financial planning isn’t just about what you leave behind. It’s also about what you get to enjoy together while you’re here . Illustrative example based on an actual insurance quote for a healthy 65-year-old woman. Actual premiums, benefits, and eligibility vary by insurer, policy terms, and underwriting
Take the grandchildren to Disney World.
Stay somewhere wonderful. Take the cruise. Buy the ridiculous souvenirs. Take too many photographs. Eat the overpriced ice cream. And create a memory those children may still be talking about decades later.
Someday they may inherit Grandma’s money. But they’ll never again have the opportunity to take that trip with Grandma.
Sometimes Money Is Supposed to Be Lived
Financial planning can become very mathematical: rates of return, tax consequences, death benefits and income. All of those things matter. But money is ultimately supposed to accomplish something. Sometimes that means providing financial security after we’re gone. Sometimes it means protecting ourselves while we’re alive. And sometimes it means going to Disney.
Leave something meaningful. Live something meaningful.
Can Life Insurance Increase a Legacy?
For the right person, properly designed life insurance can potentially turn an existing asset into a larger income-tax-free death benefit for beneficiaries under current federal tax rules. Certain policies may also provide access to benefits during life following qualifying events, depending upon the contract. But the example isn’t the recommendation. Age matters. Health matters. Liquidity matters. Taxes matter. Family circumstances matter. And the amount of money someone should keep readily available matters enormously. First we determine what that money needs to accomplish. Then we determine whether insurance improves the outcome.
Legacy planning isn’t limited to children and grandchildren. Perhaps there’s a church, university, animal rescue, or charitable organization that has been important throughout your life. Imagine a healthy 65-year-old woman who has set aside $50,000 to leave to her favorite charity. She may qualify for a single-premium life insurance policy costing approximately $35,000 that provides a $60,000 death benefit to the charity. That leaves approximately $15,000 she could donate today, while the charity remains the beneficiary of $60,000 when she passes away. Instead of waiting to make one gift, she has the opportunity to make a difference today and leave an even greater legacy tomorrow. Illustrative example based on an actual insurance quote for a healthy 65-year-old woman. Actual premiums, benefits, and eligibility vary by insurer, policy terms, and underwriting.
Tell me who matters to you. Tell me what you'd like to leave them. Tell me what you need to keep available for yourself. And tell me what you'd still like to experience while you're here. Then we'll look at the numbers. And only after that will we look at products.